Key takeaways
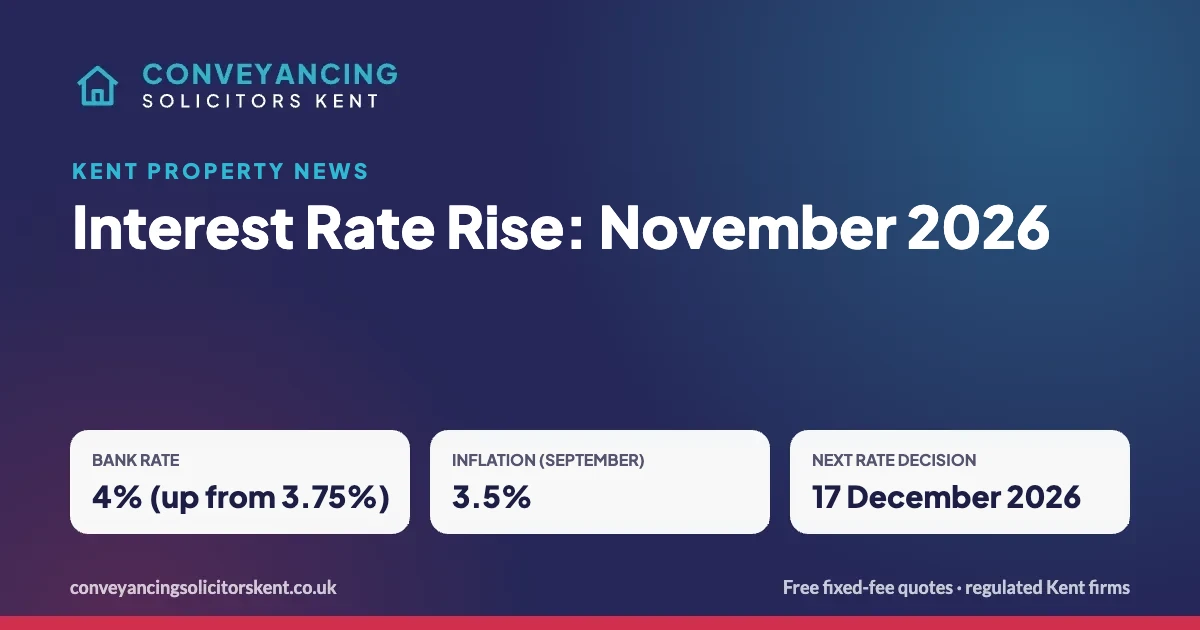
- Bank Rate rose by 0.25 percentage points to 4% on 5 November 2026, the first rise since August 2023.
- Tracker and variable-rate mortgages usually rise from the following month. Fixed rates stay the same until the deal ends.
- Lenders had largely priced the rise into new fixed rates before the decision, so today’s change is a small step rather than a jump.
- Stamp Duty is unchanged after the 28 October Budget.
- Your mortgage offer has an expiry date. A solicitor who starts promptly and keeps your chain moving helps you complete while your rate is still valid.
The interest rate rise: what the Bank of England decided
At its meeting ending on 4 November 2026, the Bank of England’s Monetary Policy Committee voted 8–1 to raise Bank Rate to 4%, with one member preferring a larger rise to 4.25%. It is the first increase since August 2023.
The Bank’s reason is inflation. Consumer prices rose by 3.5% in the year to September, and higher energy costs linked to the conflict in the Middle East are expected to push inflation to around 5% by the middle of 2027. The Bank says it is not on a pre-set path and will adjust rates as needed. The next decision is due on 17 December 2026.
What the interest rate rise means for your mortgage
- Tracker mortgages follow Bank Rate, usually from the next monthly payment. As a guide, a 0.25-point rise adds roughly £29 a month to a £200,000 repayment mortgage over 25 years, or about £36 on £250,000.
- Standard variable rates are set by each lender and often follow Bank Rate.
- Fixed rates stay the same until your deal ends. New fixed deals are priced on what markets expect rates to do, and lenders had largely built a rise to 4% into their pricing before today.
For most movers, the bigger question is the rate on a new mortgage, and a broker can compare what is available across lenders now. MoneyHelper has a free mortgage calculator if you want to check your own figures.
If you are buying in Kent
- Get a mortgage in principle so you know your budget and your offer is taken seriously.
- Apply for your mortgage as soon as your offer is accepted. Once the lender issues an offer, the rate is usually held until it expires, often around six months.
- Instruct your solicitor the same week. Searches and enquiries take time, and local search times vary between Kent’s councils.
- Check your Stamp Duty. The Budget left it unchanged. First-time buyers pay none up to £300,000, which covers a typical home in towns such as Margate, Ramsgate, Dover and Folkestone. See our Stamp Duty guide.
If you are selling in Kent
Your buyer’s mortgage offer now matters as much as their price, because it has a deadline. You can help keep the sale on track:
- Instruct a solicitor when you list, not when you accept an offer, so your contract pack is ready to send.
- Gather your paperwork early: title deeds, guarantees, building regulations and planning documents, and your leasehold information if you own a flat.
- Ask how your buyer is funding the purchase and when their mortgage offer expires, so everyone in the chain works to the same timetable.
See our guide to conveyancing for selling a house in Kent.
Why a good conveyancing solicitor matters when rates rise
When rates are moving, time has a value. A mortgage offer holds a rate for a set period, and a well-run conveyancing file makes the most of it. Here is what a good solicitor brings:
- A prompt start. Searches ordered and the contract reviewed in the first few days, rather than weeks.
- A firm on your lender’s panel. Your solicitor also acts for your lender, so check the firm is approved before you instruct.
- Clear updates across the chain. Regular contact with the agent and the other solicitors spots problems early, before they hold up exchange.
- Local knowledge. A firm that knows Kent’s councils, flood areas, leasehold flats and new-build estates can anticipate the questions your property raises.
- A fixed fee in writing. You know the cost before work starts, with any possible additional conveyancing costs explained up front.
- Proper regulation. Look for a firm regulated by the Solicitors Regulation Authority or the Council for Licensed Conveyancers. Many also hold the Law Society’s Conveyancing Quality Scheme accreditation.
Read when to instruct a conveyancing solicitor and what is included in a conveyancing quote.
If your fixed rate is ending
Most lenders let you secure a new deal several months before your current rate ends, which can protect you if rates rise again. Staying with your lender (a product transfer) usually needs no legal work. Switching lender needs a solicitor and usually takes about 2 to 4 weeks once instructed. See remortgage conveyancing in Kent.
What happens next?
The Bank of England’s survey of market participants found the median expectation was for Bank Rate to reach 4.25% in February 2027, but nothing is certain and the Bank will decide meeting by meeting. Stamp Duty and the help for first-time buyers announced in Budget 2026 are unaffected by today’s decision. We will update this page after the 17 December decision.
FAQs
Interest rate rise: FAQs for Kent movers
What is the Bank of England interest rate now?
4%. The Bank of England raised Bank Rate by 0.25 percentage points, from 3.75% to 4%, on 5 November 2026. The next decision is due on 17 December 2026.
Will my mortgage payments go up?
Only if you are on a tracker or a variable rate. Tracker rates usually rise from the following month, and many lenders also raise their standard variable rate. If you are on a fixed rate, your payments stay the same until the fixed period ends.
Should I still buy a house in Kent after the interest rate rise?
That depends on your own budget and plans, and a mortgage broker can tell you what you can borrow now. If you go ahead, secure your mortgage offer and instruct a solicitor early, so your purchase can complete while the offer and its rate are still valid.
How long does a mortgage offer last?
Often around six months, and sometimes longer for new builds. Your solicitor will aim to exchange and complete before it expires, which is why a firm that moves quickly matters more when rates are rising.
Do I need a solicitor on my lender’s panel?
Yes, if you are buying with a mortgage. Your solicitor also acts for your lender, so the firm must be on that lender’s panel. Check this before you instruct, as a firm that is not on the panel can cause delays or extra cost.
Ready when you are
Moving home in Kent? Get your quote today.
Free, fixed fees and no obligation.